Avoid a 7 Year Pension Surprise: Retirement Scenarios for Australia

Scenario planning beats guesswork because it turns “should I retire at 60 or 65?” into a side-by-side comparison of actual numbers. Build three models now: a baseline using your current savings rate, a conservative version with lower returns and higher costs, and an optimistic one with part-time income. Every version needs preservation age, Age Pension timing, the assets test, and the transfer balance cap baked in, or the projections will mislead you.
TL;DR:
- Building multiple models with conservative and optimistic assumptions is essential to understanding how market returns, spending, and retirement age affect your sustainability.
- Australian rules like preservation age, the transfer balance cap, and the assets test can significantly alter your retirement projections if not properly accounted for in scenario planning.
- Stress testing each scenario against market downturns and changes in government support timing helps identify potential shortfalls and optimal retirement strategies.
- Tools like Aerowealth, Moneysmart, and HouseGoodbye enable side-by-side comparisons of realistic retirement paths, including early versus delayed retirement options.
- Accurate modeling requires updating assumptions regularly, especially given frequent rule changes, and starting with conservative estimates offers the most reliable risk assessment.
Table of Contents
- What Should Every Retirement Scenario Include?
- How Do You Build and Compare Retirement Scenarios?
- Which Australian Rules Actually Change Your Numbers?
- What Tools Actually Help You Compare Scenarios?
- Two Scenarios: Retiring Early vs. Delaying
- Why Aerowealth Built Scenario Tools This Way
- Where Most Retirement Advice Gets This Wrong
- Try Aerowealth Free and Model Your Own Retirement Timeline
- Sources
- FAQ
What Should Every Retirement Scenario Include?
A scenario is only as good as its inputs. Miss one lever and the whole projection can tilt in a direction that doesn’t match reality.
Every model should account for:
- Assets: current super balance, other investments, property equity, and expected inheritances
- Growth assumptions: investment mix and a realistic return band, not a single optimistic figure
- Costs: fund fees, insurance premiums inside super, and ongoing advice costs
- Spending: current household spending, plus how it might shift in the first years of retirement
- Drawdown rate: how much you plan to withdraw annually, and whether that rate holds up over 25 to 30 years
- Timing: target retirement age, plus any part-time work or phased exit
- Tax events: capital gains from selling property or shares, and how that interacts with your income in the year of sale
On the output side, look for projected annual income, the point at which a shortfall might appear, when the Age Pension kicks in and at what rate, and how much of your transfer balance cap you’d use. Change one input at a time between scenarios. If you shift retirement age and drawdown rate simultaneously, you won’t know which change actually moved the outcome.
How Do You Build and Compare Retirement Scenarios?
Good retirement scenario planning follows a repeatable sequence, not a one-off spreadsheet exercise you do once and forget.
- Gather your baseline data. Pull your current super balance, any Age Pension estimate, mortgage balance, and monthly cash flow. This is the floor every scenario builds from.
- Set your core economic assumptions. Pick an inflation rate, then a return range that spans conservative, typical, and optimistic markets. Include realistic fee drag, since even a 0.5% difference compounds heavily over 20 years.
- Define your scenario levers. Retirement age, drawdown rate, and part-time earnings are the three variables that move outcomes the most. Vary each independently so you can trace exactly what caused a shift in projected income.
- Run the scenarios side by side and stress test them. Change one assumption per run and watch how sustainable income, longevity of funds, and Age Pension eligibility all respond. A market downturn in year one of retirement behaves very differently from the same downturn in year ten, so test sequencing risk, not just average returns.
When you read the output, focus on three things: whether the drawdown rate is sustainable across the full projection, whether a change in retirement age shifts your Age Pension start date, and whether any lump sum contribution pushes you near the transfer balance cap.
Thresholds and rules get reviewed multiple times a year, so a model built in January can be stale by September.*
Which Australian Rules Actually Change Your Numbers?
Three rules do most of the damage to unprepared retirement models, and each one can shift your retirement date by years if you ignore it.
Preservation age versus Age Pension age. These are two separate gates, and confusing them is the single most common mistake in DIY planning. Preservation age is 60 for anyone born after June 30, 1964, meaning that’s when your super becomes accessible. Age Pension age, on the other hand, is currently 67. A transition to retirement income stream (TRIS) can bridge that gap, letting you draw down super while still working, but it caps annual payments at 10% of your account balance and restricts lump sum access until you meet a full condition of release.

The transfer balance cap. As of July 1, 2026, you can move up to $2,100,000 into a tax-free retirement phase account. Anything above that stays in accumulation phase, where earnings are taxed. Scenarios that don’t track this cap tend to overstate tax-free income for higher-balance retirees.
The Age Pension assets test. Homeowner cut-off points for a part pension currently sit at $733,500 for singles and $1,102,500 for couples, with lower thresholds for the full pension. These figures move in scheduled reviews. So, a scenario built around today’s numbers needs revisiting later.
- Account-based pensions, annuities, and other income streams are all assessed differently under the assets and income tests, using categories like asset-tested lifetime and long-term products.
- A small shift in asset value near a threshold can flip your pension eligibility entirely, which is exactly why sensitivity testing matters more than a single “best guess” projection.
What Tools Actually Help You Compare Scenarios?
Not every calculator is built for the same job. A quick sanity check and a full retirement plan call for different tools.
Look for a platform that offers:
- Multi-scenario side-by-side views, not just one projection at a time
- Age Pension modelling that reflects current assets test thresholds
- Awareness of TRIS rules and the transfer balance cap
- Basic tax and capital gains modelling for property or share sales
- Sensitivity testing that lets you stress one assumption without rebuilding the whole model
- The ability to export your numbers for a second opinion
The Moneysmart retirement planner is a solid free starting point for a baseline check, and it’s worth running early since it’s built directly around government assumptions. But its own guidance notes results are assumption based, not predictive, which is exactly why a fuller planner earns its place once you need to compare more than one path. Another option worth testing is the HouseGoodbye retirement calculator, which projects net worth and monthly income if you want a second interactive check outside your main planner. To test any tool quickly, import your current balances, run your baseline, then delay retirement by three to five years in a second run and compare the two outputs side by side.
Two Scenarios: Retiring Early vs. Delaying
Here’s what the trade-off actually looks like when you run the numbers instead of guessing at them.
- Retire at 60 with part-time work. Income comes from a mix of TRIS drawdowns and part-time earnings, which eases pressure on your super balance in the early years. Drawdown pressure stays moderate because part-time income covers a chunk of spending, but Age Pension eligibility is still seven years away, so this phase relies entirely on your own resources and any Work Bonus offset from part-time earnings.
- Delay retirement to 67. Super keeps compounding for longer, which typically supports a higher sustainable drawdown rate once you do stop working. You also reach Age Pension age immediately, and a larger balance means more of it may sit above the transfer balance cap, pushing some funds into a taxed accumulation account rather than tax-free retirement phase.
Retiring early tends to work when part-time income is reliable and your balance can absorb a longer drawdown period without government support as backup. Delaying clearly improves sustainability when your balance is tight relative to your spending, since modelling retirement in stages rather than as one fixed date tends to reveal that income mix shifts significantly between year one and year ten regardless of which age you pick.
Why Aerowealth Built Scenario Tools This Way
Aerowealth was built around the idea that a spreadsheet can’t hold enough variables to make a real retirement decision safely. The platform runs side-by-side scenario comparisons and stress tests that fold in Australian-specific rules, including bridge-year modelling for people retiring before their super is accessible. Most readers use it the same way: import current balances, run a baseline against one alternate timeline, then stress test both against a market downturn or a delayed Age Pension start.
Where Most Retirement Advice Gets This Wrong

Most retirement content treats “when should I retire?” as a single number to solve for, when it’s actually three separate questions layered on top of each other: when can you access your money, when does government support start, and when does your balance actually support your spending. Generic advice tends to average these into one vague age recommendation, which is exactly why so many people are surprised by a seven-year gap between preservation age and Age Pension age they never modelled.
The bigger failure in conventional planning is treating a single projection as an answer rather than a starting point. A plan built on one return assumption and one retirement date isn’t a plan. It’s a guess dressed up in a spreadsheet. The reader’s first priority should be building the conservative and optimistic bookends before worrying about anything else, because that range tells you how much risk you’re actually carrying, not the average outcome. Once you know your range, adjusting for a market downturn or a delayed pension start becomes a tweak, not a crisis.
— Aerowealth Team
Try Aerowealth Free and Model Your Own Retirement Timeline
Aerowealth replaces the guesswork of a single spreadsheet projection with side-by-side scenarios that already account for preservation age, the transfer balance cap, and Age Pension thresholds, so you’re not manually rebuilding formulas every time a rule changes.
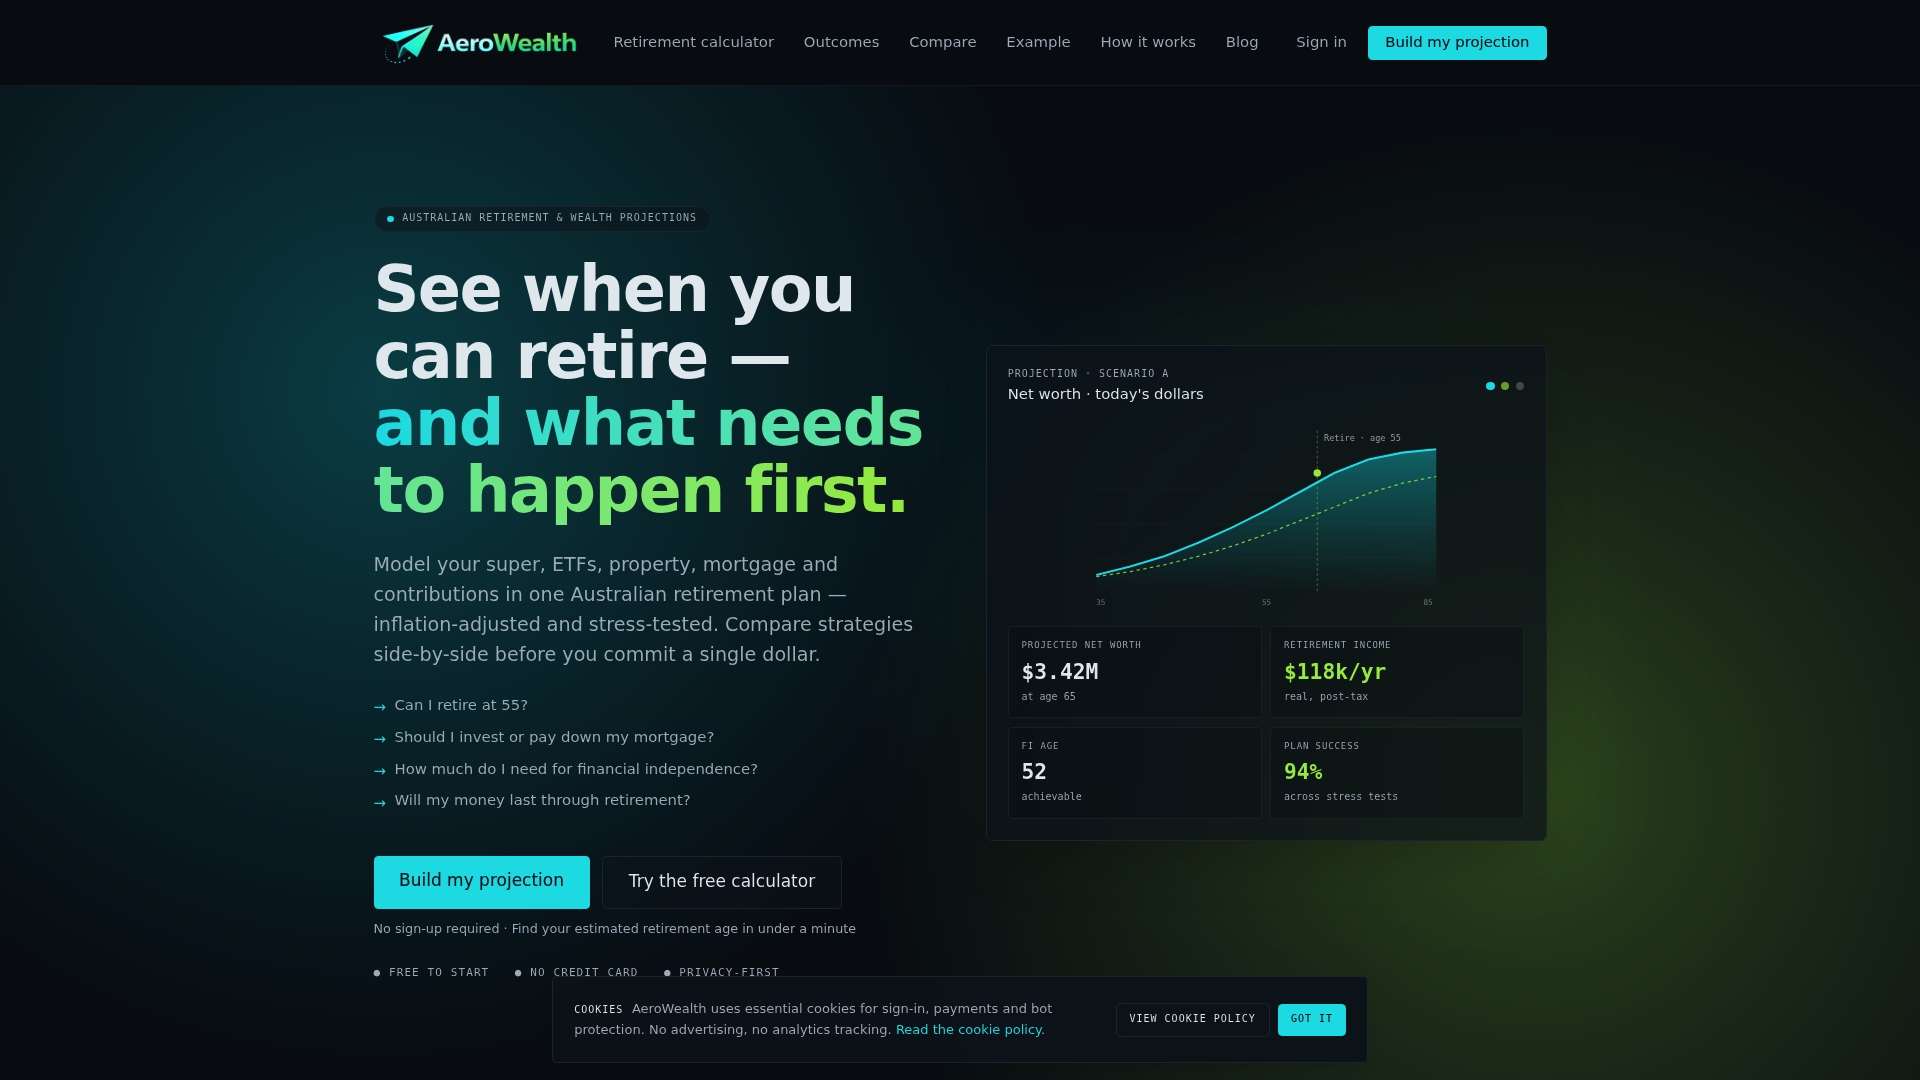
Sign up on the Free plan and import your current super balance, spending, and target retirement age to run your first baseline. From there, build a second scenario that delays retirement by a few years or adds part-time income, and compare the two outputs directly. If you want deeper stress testing, bridge-year modelling for early retirement, or expanded mortgage and CGT features, the Pro plan runs $7 AUD per month. Start on the Aerowealth homepage if you’d rather see how the platform works before creating a scenario.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Superannuation and finances when you retire (MyGov / Services Australia)
- Transition to retirement income streams (TRIS) — ATO
- Retirement planner — Moneysmart
FAQ
What Is the 7% Rule in Retirement?
There’s no single official “7% rule” recognized under Australian retirement guidance, and definitions vary depending on the source. Most references to it come from broader withdrawal rate debates, so it’s more reliable to run your own drawdown sensitivity tests using tools like the Moneysmart retirement planner than to rely on a fixed percentage.
How Much Super Do I Need to Retire on $70,000 a Year?
The answer depends heavily on your drawdown rate, investment returns, and whether the Age Pension supplements your income later on. Rather than relying on a flat figure, model your own scenario with your actual balance and spending, since a sustainable drawdown rate shifts significantly based on market conditions and retirement age.
What Are Signs It Might Be Time to Retire?
There’s no universal ten-point checklist backed by official guidance, but the clearest signal is that your scenario modelling shows a sustainable income across a conservative return assumption, not just an optimistic one. If your projected drawdown holds up under a stress test and your Age Pension timing is factored in, that’s a stronger signal than any general checklist.
What Is the 50/30/20 Rule for Retirement?
General budgeting guidelines typically split income into needs, wants, and savings rather than applying a retirement-specific formula. Such rules can help structure pre-retirement saving but do not account for Australian-specific factors like preservation age or the Age Pension assets test, so they work better as a budgeting starting point than a retirement projection tool.
Can Aerowealth Model Both Early Retirement and Delayed Retirement?
Yes. Aerowealth is built to run side-by-side scenarios, including bridge-year modelling for retiring before your super is accessible and comparisons against a delayed retirement timeline. You can test both against the same stress assumptions to see which one holds up better under a market downturn.