Negative Gearing in Retirement: Cash Flow, Tax and Age Pension

Negative gearing is harder to run in retirement than during your working years. The tax deduction depends on having other taxable income to offset, and once your salary stops that income often disappears. The Age Pension tests also don’t give you credit for the loss. Whether to keep, reduce or sell a geared property depends on your cash flow, your tax position and the purchase date of the property. This guide walks through each, then shows how to model the choices before you commit.
TL;DR
- Negative gearing creates a tax deduction only if you have other assessable income to absorb the loss. Super pension income after 60 is generally tax-free, so it can’t do that job.
- For the Age Pension income test, a rental loss is counted as zero and can’t be offset against your other income. The assets test counts the property at market value less the debt secured against it.
- Budget 2026-27 changes to negative gearing start on 1 July 2027 and turn on the purchase date, so check when you bought.
- Model the wind-down years before you retire, including interest-only loan expiry, rate rises and vacancy, rather than relying on one projection.
Table of Contents
- What negative gearing is, and why retirement changes the maths
- What happens to the cash flow when the salary stops
- Super, tax and the loss you can’t use
- How negative gearing interacts with the Age Pension
- The 2026-27 Budget changes and the purchase date
- Retiring before preservation age: the bridge years
- Keep, reduce or sell: a way to decide
- What a negative gearing calculator should include
- Perspective
- Model your own wind-down
- FAQ
- Sources
What negative gearing is, and why retirement changes the maths
Negative gearing occurs when the deductible expenses of an investment exceed the income it earns. The resulting loss can be used as a deduction against other assessable income such as salary, which lowers your taxable income, as Treasury explains. Moneysmart describes the same strategy from the borrowing side: you borrow to invest, and the rental income is lower than costs such as loan repayments and repairs.
The important word is “offset”. The deduction is only worth something if there is taxable income for it to reduce. A person on a high marginal rate who is still working gets a meaningful tax reduction on each dollar of loss. The cash is still going out of their pocket, though. Negative gearing reduces a loss, it doesn’t turn it into a gain.
That is why retirement is a turning point. National Seniors Australia notes that gearing can magnify gains and losses, that debt, interest and charges must be repaid, and that investment income can vary or even be nil. It also says adequate income to meet loan commitments is important, and that the strategy suits investors with surplus disposable income and higher marginal tax rates. Many retirees have neither.

What happens to the cash flow when the salary stops
While you work, your salary pays the shortfall on the property and absorbs the tax loss. At retirement two things change at once. Your income falls, so the shortfall is harder to fund. And the tax benefit shrinks, because there is less taxable income to deduct against.
One adviser analysis describes the typical pressure this way: salary that once absorbed the losses ends, super pension income is often tax-free, and retirees may need to cut debt or sell geared assets to avoid shortfalls and the risk of being forced to sell in a market downturn.
Moneysmart lists mortgage payments, rates and insurance among essential costs and warns that stopping work can make loan repayments harder to keep up. For a geared investor, the property loan is a second set of essential costs on top of your own living expenses.
Interest-only loans and the repayment step-up
Many investment loans are interest-only, which keeps repayments low while the loan is geared. Moneysmart points out that an interest-only loan doesn’t reduce the principal during the interest-only period, and that repayments rise when principal-and-interest repayments begin. If that step-up lands in the first years of retirement, it lands when your income is lowest.
This is exactly the kind of event worth stress testing. A walk-through of property cash flow stress testing shows how an investor can look at an interest-only loan expiring alongside rate rises and vacancy, using an overseas example. The method carries across to Australian properties.
Super, tax and the loss you can’t use
For retirees over 60, super pension income is tax-free and excluded from assessable income. It therefore gives a rental loss nothing to offset, according to the same adviser analysis. Unused losses may be carried forward under ordinary tax-loss rules, so they aren’t necessarily wasted, but they don’t help your cash flow today.
If most of your wealth sits in super, negative gearing is a weaker fit. If you still have some taxable income, for example from part-time work, a part-year of employment, or other investments, the deduction keeps some value. This is why the timing of retirement within a financial year can matter.
Senior tax offsets and the add-back
A rental loss does not always lower the income measures used for senior benefits. The ATO’s 2025 instructions include net rental property losses in rebate income. That means the loss can push up the income figure used for some senior tax offset eligibility rather than pulling it down. A 2026 analysis of the Seniors and Pensioners Tax Offset makes the same point: total net investment losses are added back to taxable income for the SAPTO income test, which can reduce or remove the offset.
The Department of Social Services says a net rental property loss is added back for Commonwealth Seniors Health Card income testing. A tax loss doesn’t necessarily reduce assessable income for that card either.
How negative gearing interacts with the Age Pension
The Age Pension has two tests, and the lower result applies. A geared property touches both.
The income test
Services Australia counts the net income from a rental property, but it doesn’t allow rental losses to be offset against income from other sources. If the property makes a loss, that income is counted as zero. So the loss that cuts your tax bill does nothing to improve your pension, and your pension income test doesn’t reward the gearing. For worked examples, see our walk-through of how rental income affects your Age Pension, and our income test explainer.
The assets test
Under the assets test, rental properties are counted at market value, and the debt secured against the property is deducted from the value. This applies whether or not the property is negatively geared. Paying down the loan therefore raises your assessed assets dollar for dollar, while selling the property and converting it into other assets changes how they’re counted. If you hold cash in a mortgage offset account, see how offset balances are treated in the assets test. The current limits are set out in our assets test thresholds guide.
A simple example shows how the tests pull in different directions. Suppose you hold a property worth $800,000 with a $400,000 loan. For the assets test it counts as $400,000. If you use a lump sum from super to clear the loan, the property counts as $800,000, but the money you took from super no longer counts, so the net effect on assets depends on what else moves. Your income test result is unchanged by a loss either way. Putting actual numbers on this is the job for a model, not a rule of thumb.

The 2026-27 Budget changes and the purchase date
The Budget 2026-27 tax explainer sets out the changes. From 1 July 2027, established residential properties bought between 7:30pm AEST on 12 May 2026 and 30 June 2027 can no longer be negatively geared. Losses can only be used against residential property income, including capital gains, with any excess carried forward. Properties bought from 1 July 2027 cannot be negatively geared at all.
The rules are framed around purchase date, so your first step is to find the contract date of each property you hold. Two points follow for retirees:
- If you are considering buying an investment property late in your career as a retirement income source, the gearing deduction may not be available to you, so the numbers need to work without it.
- If you hold an older property, the wind-down timeline is yours to choose, but the capital gains side deserves its own modelling. Our guide to the CGT discount changes ahead of 1 July 2027 covers that.
The measures are Budget announcements and details can move, so confirm the current position on the official Budget and ATO pages and with a registered tax agent before acting.
Retiring before preservation age: the bridge years
If you plan to stop work before you can reach your super, a geared property can become a heavy load. Your super isn’t yet available, and your salary has gone. The ATO says super can generally be withdrawn at age 65, or earlier once you’ve reached your preservation age and retired, or under another condition of release. Preservation age is different from Age Pension age.
The temptation to reach for super early is real, but the ATO is explicit that accessing super before a condition of release is illegal and can result in the amount being added to your taxable income, plus extra tax, penalties and interest. So the bridge years have to be funded from assets outside super: cash, an offset account, ETFs, rent or sale proceeds.
That makes the question concrete. How many years is the gap, what does the property cost you each year over that gap, and which assets cover it? A geared property that loses $12,000 a year after tax across a seven-year gap costs $84,000 before any rate rise, which is a number you want to see in advance.
Keep, reduce or sell: a way to decide
A common approach for geared investors approaching retirement is a multi-year wind-down, often spanning 5 to 7 years, using super lump sums, asset sales and a move to ungeared investments to reduce debt. It is a pattern, not a rule, and your own timeline will differ. The questions to work through are:
- When did I buy? The purchase date decides how the 2027 changes apply.
- Can I fund the shortfall without salary? Include repairs, vacancy, insurance and rates.
- When does the interest-only period end? Model the repayment step-up.
- What happens to my Age Pension? Check both tests, with and without the property.
- What is the tax on selling? Capital gains tax and timing matter, particularly in a year with less other income.
- Do I need the income, or the growth? A property you hold for growth but can’t afford to carry is a risk.
Each of these changes the others. Selling lowers the shortfall but triggers tax and raises liquid assets for the pension tests. Paying down debt lowers interest but raises assessed assets. This is why people get stuck with a spreadsheet: change one cell, and four others need hand-correcting.
What a negative gearing calculator should include
A useful calculator takes inputs such as interest rates, vacancy, ownership shares and property expenses, and tests rate rises, vacancy, rent falls and expense shocks. One lender’s investor deal analyser is built this way, and it states that its tax figures are estimates, not tax advice.
When you compare scenarios, don’t mistake a tax saving for an investment gain. Compare:
| Measure | What it tells you |
|---|---|
| Operating cash flow | Rent less running costs, before the loan |
| Cash flow after interest | What the loan costs you each year |
| Cash contribution after full repayments | What you must find from other money, including principal |
| After-tax figure | An estimate that depends on your marginal rate and the property’s gearing treatment |
The same analyser notes that the after-tax figure is an estimate based on each owner’s marginal rate and the property’s treatment. For a retiree the checklist is longer. A tool for this stage of life should also handle:
- Super pension income, and the point at which it becomes tax-free
- Age Pension income and assets tests alongside the property
- A change in your marginal tax rate after you stop work
- Capital gains tax if you sell in a given year
- Bridge years before preservation age
- Interest-only expiry and rate rises
If you want to know which deductions you can actually claim while the property is still geared, read our guide to investment property tax write-offs.
Perspective
Most retirement tools treat an investment property as one number: a value, maybe a yield. That hides what matters. A geared property sits in three places at once: your cash flow, your tax return and your Age Pension assessment, and a decision in one moves the others.
We built AeroWealth to hold those pieces in one plan. You can put super, an investment property, ETFs, a mortgage and contributions side by side, then compare scenarios such as keeping the property, selling it in year three, or paying down the loan from savings. Our stress tests are designed to show what happens if rates rise or assumptions turn out wrong, and our bridge mode models the years between retiring and reaching your super.
Our view is that the right answer for a geared retiree is rarely “hold” or “sell” in the abstract. It is a specific timeline with a specific funding source, tested against the bad years as well as the good ones. Seeing that on one screen is the point.
Aerowealth Team
Model your own wind-down
If you hold a geared property and are within a decade of retiring, try the numbers on your own situation. AeroWealth lets you build your plan with super, property, mortgage and ETFs, then compare scenarios side by side and stress test the assumptions. There is a free plan to start with, and Pro is A$7 per month if you want expanded scenario planning, bridge mode for early retirement, advanced mortgage features and a higher AI assistant quota. See the plans and pricing, or start from the AeroWealth home page.
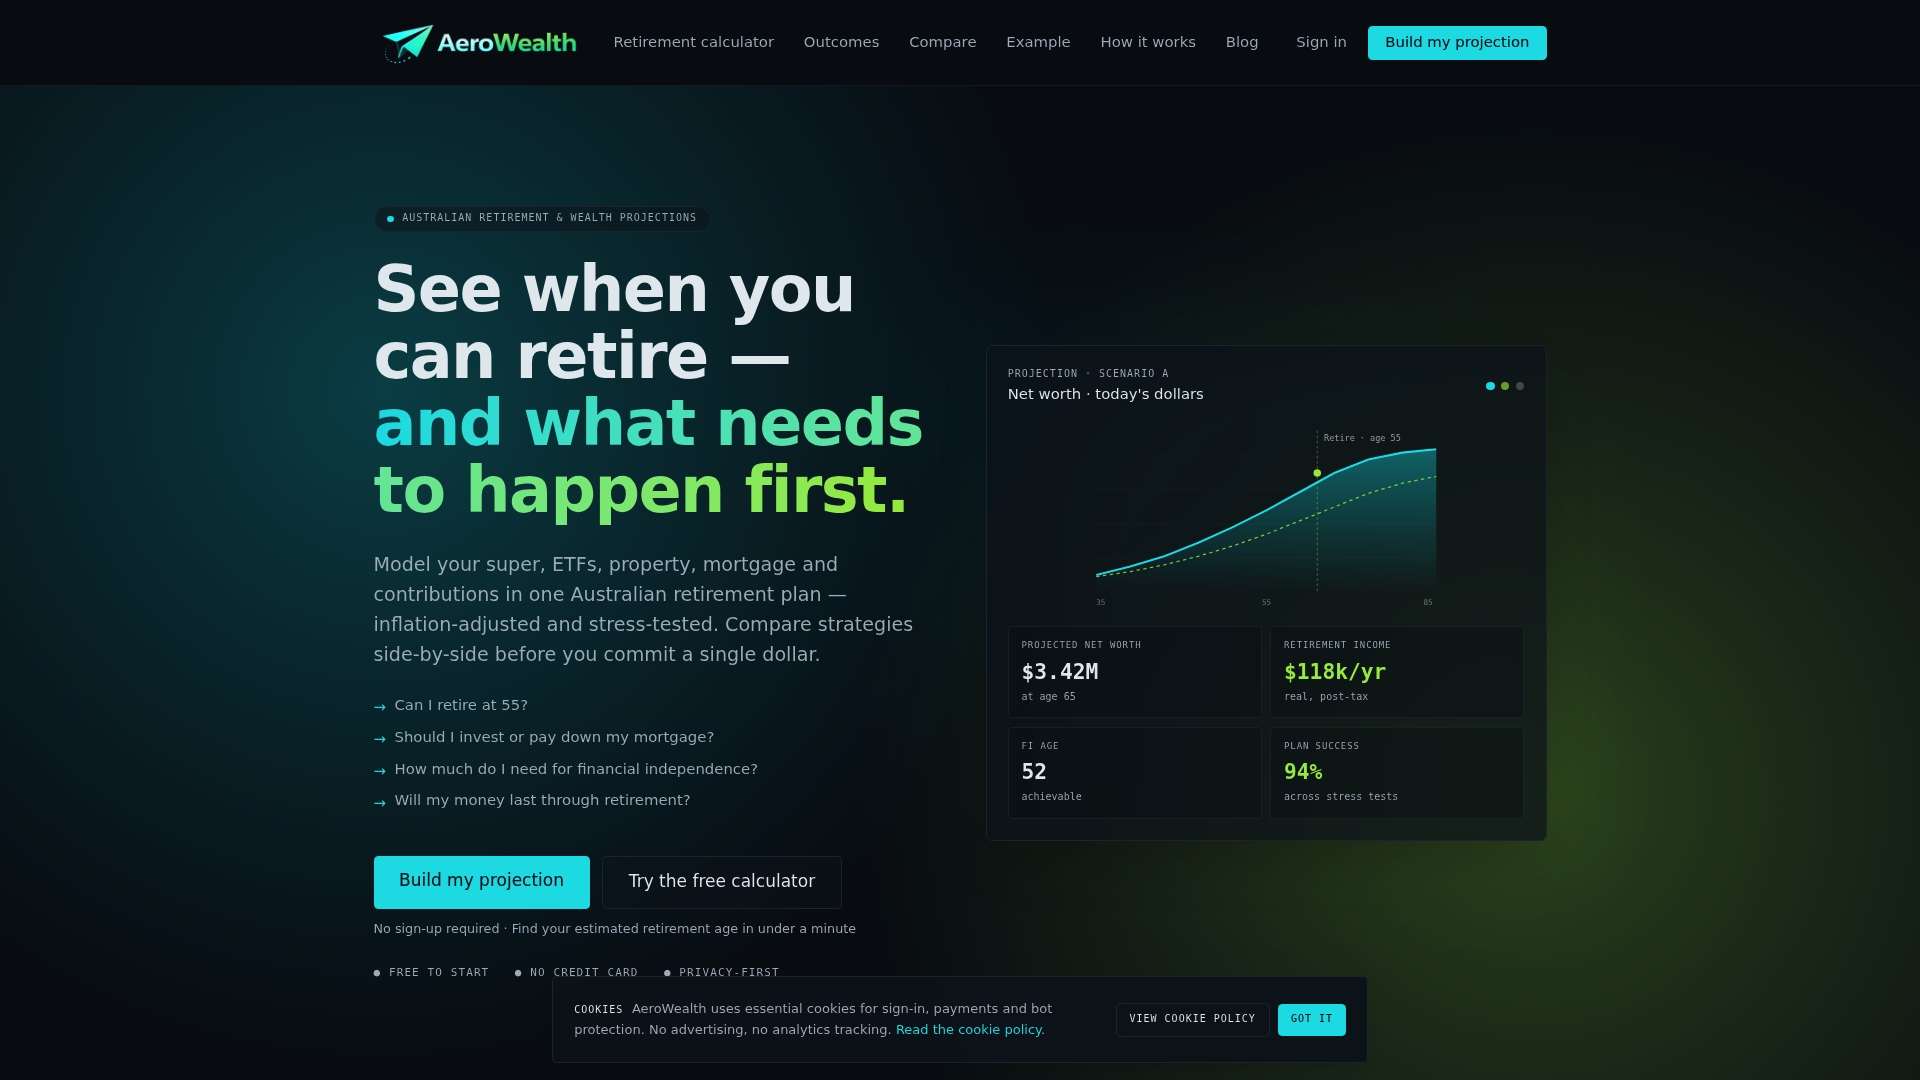
The AI assistant explains projections under Australian rules, which helps when you want to understand why a result moved, not just that it did. It’s a planning tool, not personal financial or tax advice, so take your final numbers to a registered tax agent or licensed financial adviser.
FAQ
Can I still claim a rental loss if I’m retired?
Yes, the expenses remain deductible, but the benefit depends on having other assessable income to offset. Super pension income for retirees over 60 is generally tax-free, so it doesn’t absorb the loss. Unused losses may be carried forward under ordinary tax-loss rules, so ask a registered tax agent how that applies to you.
Does negative gearing help me qualify for a higher Age Pension?
No. For the income test, Services Australia counts a rental loss as zero and doesn’t let it offset your other income. For the assets test, the property counts at market value less the secured debt, whether or not it’s negatively geared. The loss helps your tax return only.
Do the 2027 negative gearing changes apply to a property I already own?
The changes depend on the purchase date. The Budget explainer treats established residential properties bought from 7:30pm AEST on 12 May 2026 differently from earlier purchases, and properties bought from 1 July 2027 can’t be negatively geared. Check the official Budget and ATO pages for the current detail, and confirm your contract date.
Can I use my super to pay off a geared property before preservation age?
Not before a condition of release. The ATO says early access is illegal and can lead to the amount being taxed, plus penalties and interest. Fund the gap from assets outside super, or reduce the debt before you stop work.
What should I compare when using a negative gearing calculator?
Compare cash flow after interest and your cash contribution after full repayments, not just the after-tax figure. The tax figure is an estimate based on your marginal rate. Run rate rises, vacancy and an interest-only expiry so you see the bad years too.
Sources
- Negative gearing, Treasury
- Negative gearing, Moneysmart glossary
- Negative gearing, National Seniors Australia
- Negative gearing wind-down before retirement
- Managing unexpected retirement, Moneysmart
- Interest-only home loans, Moneysmart
- Property cash flow stress testing example
- Rebate income 2025, ATO
- Age Pension and net investment loss income tests
- Total net investment loss, Department of Social Services
- Real estate income, Services Australia
- Age Pension claim information
- Budget 2026-27 tax explainer
- When you can withdraw your super, ATO
- Illegal early access to super, ATO
- Investor deal analyser