Parcel Selection for CGT in Australia: How to Choose

If you bought the same shares in several lots and now sell only some of them, you can usually choose which parcel you sold. That choice changes your capital gain, your 50% discount and how much of a capital loss you use. FIFO is not compulsory: the ATO’s TD 33 says the Commissioner will accept your selection of which shares were disposed of, as long as your records support it. Modeling the sale before you place the order is the practical way to see the difference. That is what we built AeroWealth to do, with CGT and tax impact in the same plan as your super, property and mortgage.
TL;DR
- Each parcel is its own CGT asset with its own cost base and purchase date, so which parcel you sell decides the gain or loss.
- FIFO is an accepted fallback when shares cannot be told apart. It is not an obligation, and you do not register a method with the ATO.
- Parcels held 12 months or more can qualify for the 50% discount, but the lowest taxable gain is not always the oldest parcel.
- Apply capital losses before the discount, and keep records that show which parcel you sold, made around the time of the sale.
- Model two or three parcel choices side by side before you sell, then keep the evidence for at least 5 years.
Table of Contents
- What parcel selection means
- Is FIFO the rule? What TD 33 says
- How the parcel you pick changes the tax
- A worked example
- Capital losses and the order of operations
- Records that support your parcel choice
- When the sale is reported
- The 2027 discount change and why it raises the stakes
- Build parcel choices into your wider plan
- Our view: decide on the plan, not on the tax bill
- FAQ
- Sources
What parcel selection means
A parcel is a distinct number of shares bought at one time. Buy 500 shares of a company in March and another 300 in September, and you hold two parcels. The ATO treats each parcel as a separate CGT asset, so you need to keep details for each one.
The issue appears when you sell only part of the holding. Different parcels have different costs, and the ATO says you need to be able to identify which shares you sold and when you acquired them, because those costs affect the capital gain or loss. Selling all of a holding makes this question disappear. Selling part of it is where parcel selection matters.
This is easy to overlook for anyone who buys regularly: a monthly ETF or share purchase plan, dividend reinvestment, or top-ups after a market dip. After a few years you may hold dozens of parcels bought at very different prices.
Is FIFO the rule? What TD 33 says
No. TD 33 says that where you can identify which particular shares you disposed of, that identification is used. First-in, first-out is accepted as a reasonable basis when shares cannot be individually distinguished. It is a fallback, not a duty.
There is also no election form and no approval process. What the ATO looks for is evidence: records that let you show which parcel you sold. Without them, FIFO is the basis that remains.
Two related points are worth knowing:
- Average cost is generally not accepted. TD 33 allows it only where the shares are in the same company, were acquired on the same day, and carry identical rights and obligations.
- You can use different methods for different sales. The ATO’s guidance on selling shares or units names FIFO, LIFO (last in, first out) and HIFO (highest in, first out) as common ordering methods, and says a different method may be applied to each parcel sold.
The record-keeping side matters as much as the choice. TD 33 expects you to keep adequate records so the decision can be supported if your return is reviewed later.
How the parcel you pick changes the tax
The gain or loss on a parcel is the sale proceeds minus that parcel’s cost base. Because each share is a separate CGT asset, the ATO’s capital gain or capital loss worksheet notes you can use different methods for shares within a parcel, which may help if you have capital losses to apply.
Three things drive the result:
- Cost base. A higher cost base means a smaller gain, or a loss.
- Holding period. Resident individuals who own an asset for at least 12 months can reduce the net capital gain by 50%. Assets held under 12 months get no discount.
- Your other gains and losses that year. Losses are applied before the discount, which changes which parcel is best.
The key lesson is that the oldest parcel is not automatically the best, and neither is the cheapest-looking one. The discount can make an older, lower-cost parcel attractive, but a recent parcel bought near today’s price can produce such a small gain that it beats the discounted gain on the old one.
A worked example
The numbers below are illustrative, ignore brokerage, and assume you are an Australian resident individual.
You hold shares in one company:
- Parcel A: 1,000 shares bought three years ago at $8 each (cost base $8,000)
- Parcel B: 1,000 shares bought six months ago at $18 each (cost base $18,000)
You sell 1,000 shares at $20, for proceeds of $20,000.
| Choice | Capital gain | Discount | Taxable gain |
|---|---|---|---|
| FIFO (Parcel A, oldest first) | $12,000 | 50% (held over 12 months) | $6,000 |
| LIFO (Parcel B, newest first) | $2,000 | None (held under 12 months) | $2,000 |
Here the newer parcel gives the lower taxable gain, even though it misses the discount. Change the prices and the answer flips. If Parcel B had cost $11 per share, its gain would be $9,000 with no discount, which is worse than Parcel A’s $6,000.
That is why a rule of thumb like “always sell the highest cost parcel” or “always use the discount” fails. You have to run the numbers for each parcel against your actual situation.
Capital losses and the order of operations
Parcel selection interacts with losses, so the order matters. According to the ATO’s guidance on using capital losses:
- Capital losses can only reduce capital gains. They cannot reduce salary or other income.
- Unused net capital losses carry forward indefinitely to reduce future capital gains.
- You can choose which capital gains to subtract current year losses from.
- If you have gains that are not eligible for the discount, subtract losses from those first, which results in the lowest payable CGT.
The worksheet adds that you apply capital losses to your gains before you apply the CGT discount.
A short example using the numbers above: say you also have a $2,000 capital loss from another sale. If you sold the discount-eligible Parcel A for a $12,000 gain, the loss reduces it to $10,000 and the discount takes it to $5,000. If you instead sold Parcel B for a $2,000 gain with no discount, the loss wipes it out completely. Which combination suits you depends on what else you hold and what losses you are carrying forward.
Sometimes the smarter move is not minimizing tax today. If you have carried-forward losses sitting unused, realizing a larger gain this year can put them to work. That is a planning decision, and it is easier to make when you can see several years at once. Our guide to tax loss harvesting in Australia covers how losses fit into a wider plan, and our piece on wash sales in Australia explains why selling and rebuying quickly to crystallize a loss needs care.
Records that support your parcel choice
A parcel choice is only as good as the paper behind it. The ATO says you need to keep records for 5 years after the CGT event. If you carry forward a net capital loss, keep records relevant to it too. The ATO’s guidance on shares and units adds that after a carried-forward loss is offset against a gain, you should keep records for a further 2 years.
For shares and units, the ATO’s personal investors guide lists records that generally include:
- the date you bought the shares or units and the amount paid
- details of any non-assessable payments
- the date and amount of any calls, if shares were partly paid
- the sale price
- any commissions paid to brokers
- any merger or demerger of your share or unit trust
The ATO’s Guide to capital gains tax adds that records must be in English or readily translatable, and must show what happened, the day, the parties and how it relates to the gain or loss. Penalties can apply if you do not keep them for at least 5 years.
Timing is the part people get wrong. The identification should be made at or around the time of the sale, not months later when the return is being prepared and you pick whichever parcel gives the best answer. A practical routine:
- Before you sell, list every parcel with its date and cost.
- Decide which parcel you are selling and write it down (a dated note or saved file is enough).
- Place the sale, then save the contract note showing the date and price.
- Store the note with the parcel list, so your accountant can see the decision was made at the time.
If you trade frequently, the same discipline applies at a larger scale. This copy trading tax records piece makes the case for monthly record routines, which is a habit worth borrowing for parcel-level share records too.
When the sale is reported
A CGT event happens when you sell shares during the income year, which runs 1 July to 30 June. When you sell to someone else, the event happens when you enter the contract of sale, not when the money settles. That date decides which year you report the gain or loss in.
This matters for timing near 30 June. A contract signed on 29 June belongs in that year’s return. You report total current year capital gains, net capital losses carried forward and the net capital gain in the return for the year you disposed of the shares.
The 2027 discount change and why it raises the stakes
The 50% discount is under reform. According to a summary from an Australian accounting firm, from 1 July 2027 the general discount is set to be replaced for relevant new gains by an inflation-based system with a minimum 30% tax rate on real gains, with gains accrued before that date keeping the existing treatment under transitional rules. Check the ATO and Treasury pages for the final rules before acting.
For anyone with several parcels, this makes the parcel decision more consequential: the tax treatment of a given parcel can depend on when its gains accrue. We cover the planning side in Lock Gains Before 1 July 2027, and our investor’s guide to CGT on shares covers the basics if you are new to the topic.
Build parcel choices into your wider plan
A parcel decision is rarely just a tax question. A larger gain this year can push you into a higher bracket, change what you can afford to contribute to super, or alter how long your savings last in early retirement. Seeing one sale in isolation hides those effects.

AeroWealth is built for Australians who want to see them together. You model super, investment property, ETFs, mortgages and contributions in one plan, compare scenarios side by side, stress-test your assumptions and see the CGT and tax impact on your projected retirement age, income and net worth.
The Free plan lets you start modeling. Pro is A$7 per month and adds expanded scenario planning, bridge mode for early retirement, advanced mortgage features and a higher AI assistant quota. The assistant explains projections under Australian rules. You can see both on the pricing page, or start from the AeroWealth home page.
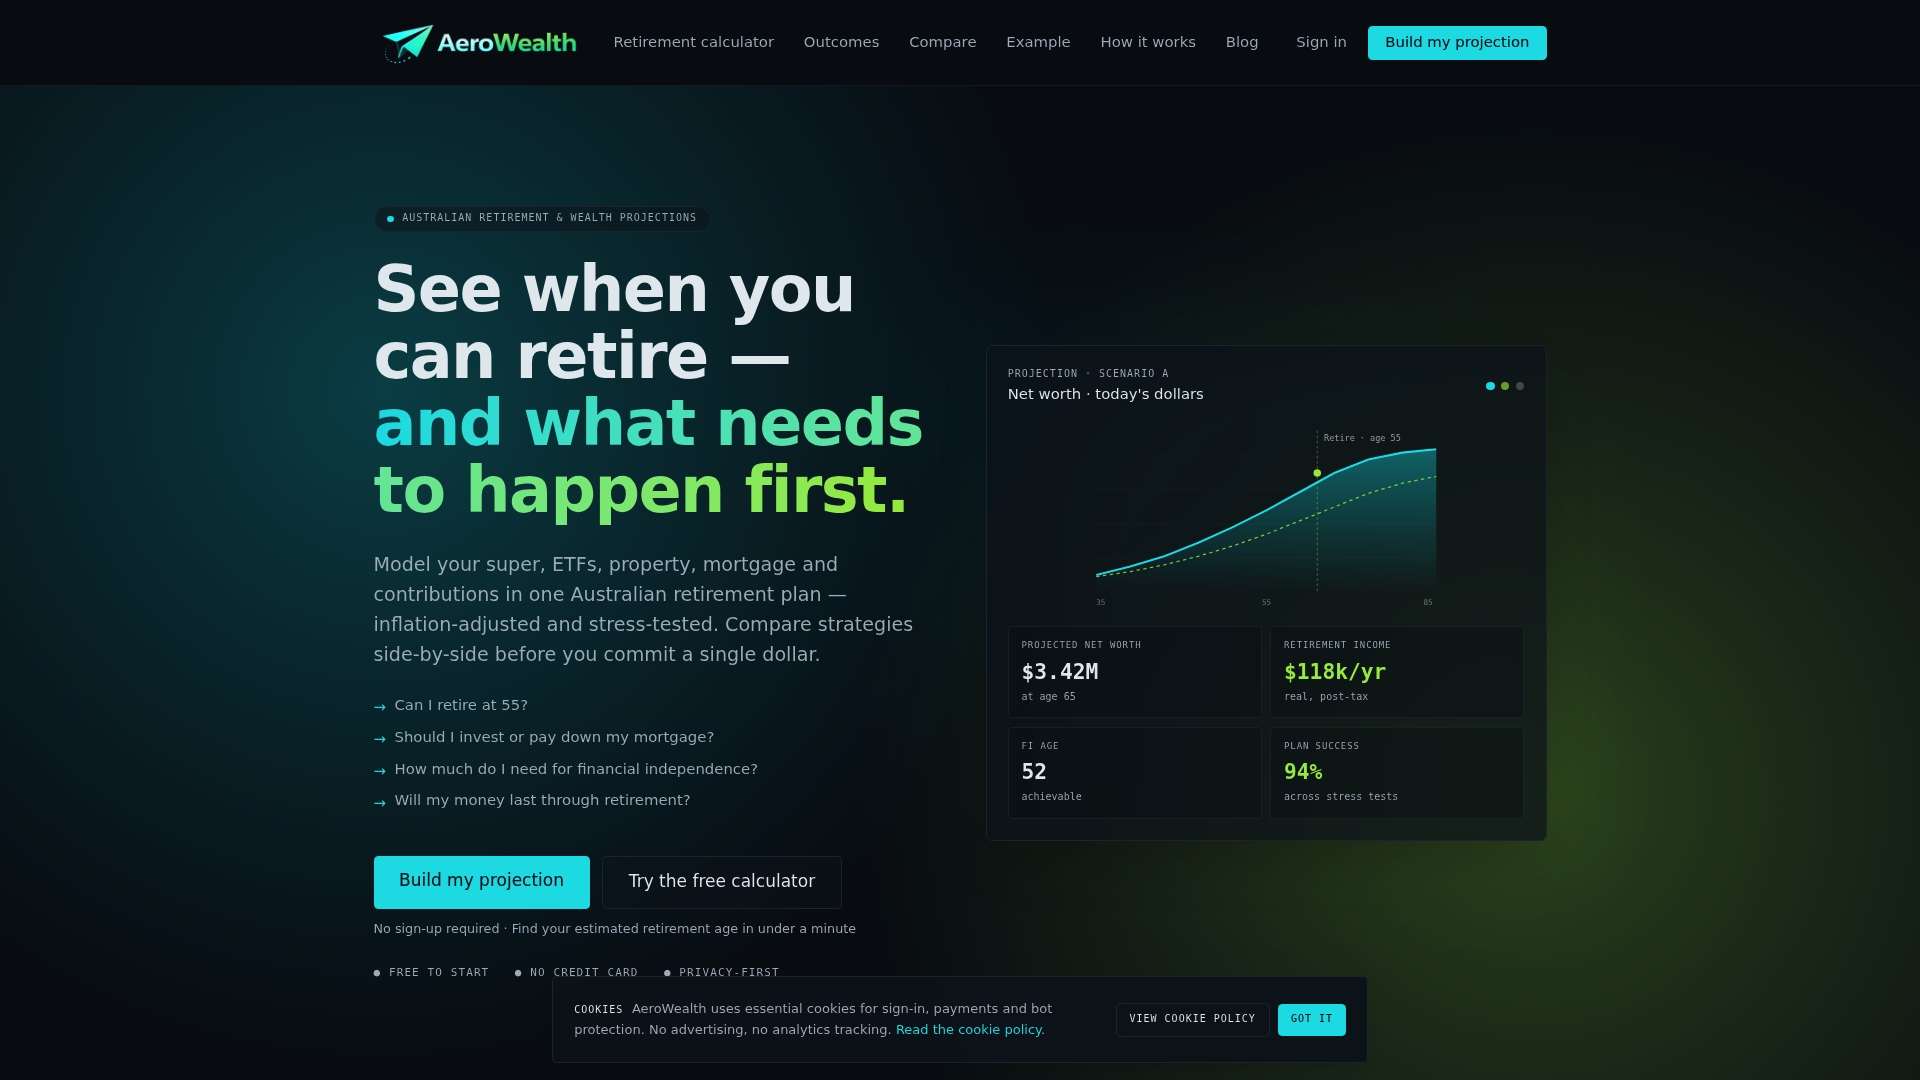
Before a sale, a useful scenario set is simple: run the sale under FIFO, run it under the parcel with the lowest taxable gain, and run it again with a carried-forward loss applied. Comparing the three side by side shows you what the choice is worth in dollars.
Our view: decide on the plan, not on the tax bill
Parcel selection is a good example of a decision that looks small and is not. One sale, one choice of parcel, and the tax result can differ by thousands of dollars. Spreadsheets handle a single sale reasonably well, but they get unwieldy when you want to see how that choice feeds through to several years of income, super contributions and a retirement date.
We designed AeroWealth around side-by-side scenario comparisons and stress tests so that you can look at a choice like this before you make it. Our CGT and tax impact modeling sits in the same plan as your super, property and mortgage, so the effect of a sale on your retirement age, income and net worth is visible in one place.
For people planning to retire before preservation age, the stakes are higher still, because the shares you sell today may be funding your bridge years. Bridge mode in Pro is built for exactly that, so you can test how much you can draw, from which assets, and when.
Aerowealth Team
FAQ
Do I have to use FIFO when I sell shares in Australia?
No. FIFO is accepted by the ATO as a reasonable basis where shares cannot be individually identified, but TD 33 also accepts your own selection where you can identify which shares you sold. You do not need to register a method. You do need records that support the parcel you say you sold.
Can I use a different parcel method for each sale?
Yes. The ATO says a different method of parcel selection may be applied for each parcel of shares sold. Keep the reasoning and records for each sale, because each is assessed on its own evidence.
Is it better to sell the parcel with the highest cost base?
Not always. A high cost base gives a smaller gain, but a parcel held over 12 months can qualify for the 50% discount. Compare the taxable gain on each parcel after losses and the discount, and consider carried-forward losses you may want to use.
How long do I keep records of parcels I sold?
At least 5 years after the CGT event, according to the ATO. If you made a capital loss, keep the records until a further 2 years after you have offset it against a gain.
Sources
- ATO: TD 33, identity of shares disposed of
- ATO: Keeping records of shares and units
- ATO: Capital gains tax on sale of shares or units
- ATO: Capital gain or capital loss worksheet 2026
- ATO: How to calculate your CGT
- ATO: Using capital losses to reduce capital gains
- ATO: Personal investors guide to capital gains tax 2025
- ATO: Guide to capital gains tax
- Dolman Bateman: New CGT rules for shares from 1 July 2027
- Copy trading tax records